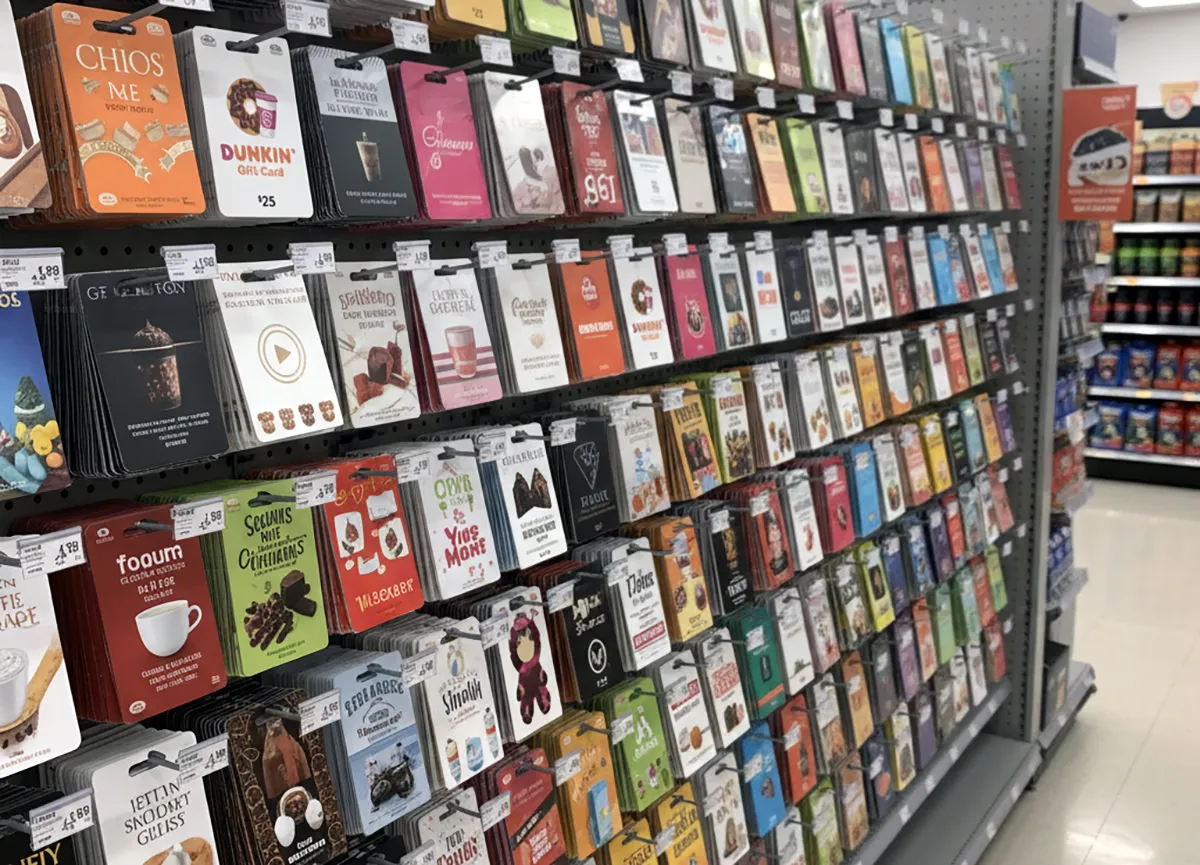
Money on a gift card bought in the United States cannot expire for at least five years under the federal Credit CARD Act, and inactivity fees are allowed only after a year without use. Thirty-eight states add their own rules: several, including California, Florida and Washington, ban expiration dates outright, and 14 require stores to pay out small leftover balances in cash, from under $1 in Rhode Island and Vermont to under $15 in California.
The Federal Rules That Apply Everywhere
Since August 22, 2010, the Credit CARD Act and the CFPB’s Regulation E (15 U.S.C. 1693l-1 and 12 C.F.R. 1005.20) have set a nationwide floor for gift cards:• The money cannot expire for at least 5 years from the date the card was bought or money was last loaded onto it.
• Dormancy, inactivity and service fees are allowed only after 12 months with no activity, no more than one fee a month, and only if the fee is clearly disclosed on the card and before purchase.
• The plastic card can expire before the money does. The issuer has to provide a way to get a replacement, free unless the card was lost or stolen.
The federal rules cover store gift cards, gift certificates sold by a single merchant or group of affiliated merchants, and general-use prepaid gift cards that work wherever a card network is accepted. They do not cover loyalty, award or promotional cards, reloadable cards not marketed as gift cards, paper-only certificates, or cards good only for admission to an event or venue. As the CFPB puts it, if a card isn’t sold as a gift card, the federal gift card rules don’t apply.
States may go further. Federal law treats a state rule as consistent with it when the state rule gives consumers more protection, which is why a card bought in California can carry very different terms from one bought in Missouri. Where a state rule is weaker — a shorter expiration minimum, for instance — the federal 5-year rule still governs any card it covers.
Gift Card Laws by State
In the table, “Expiration” is how long the money must last, “Fees” covers dormancy, inactivity and service fees, and “Cash back” is the leftover balance a store must pay out in cash on request. Each row reflects the statute as of October 2026.| State | Expiration | Fees | Cash Back | Law |
|---|---|---|---|---|
| Alabama | 5 years (federal rule) | Federal limits only | Not required | No state gift card law found |
| Alaska | 5 years (federal rule) | Federal limits only | Not required | No state gift card law found |
| Arizona | Funds never expire; card may, with a replacement | No fees of any kind | Not required | A.R.S. § 44-7402 |
| Arkansas | 5 years (federal; state minimum is 2) | None in the first 2 years; later only if printed on the card | Not required | Ark. Code § 4-88-703 |
| California | Banned (limited exceptions) | No service fees; narrow dormancy fee only on balances of $5 or less | Under $15 (since April 1, 2026) | Cal. Civ. Code § 1749.5 |
| Colorado | 5 years (federal rule) | All fees banned | $5 or less | C.R.S. § 6-1-722 |
| Connecticut | Banned | Dormancy and inactivity fees banned | Under $5, after a purchase | Conn. Gen. Stat. §§ 42-460, 42-461, 3-65c |
| Delaware | 5 years (federal rule) | Federal limits only | Not required | No state gift card law found |
| Florida | Banned (narrow exceptions) | All fees after the sale banned | Not required | Fla. Stat. § 501.95 |
| Georgia | Must be printed; 5 years (federal) | Must be printed on the card | Not required | O.C.G.A. § 10-1-393(b)(33) |
| Hawaii | At least 5 years (paper certificates 2) | Service and dormancy fees banned; activation fee up to $5 or 10% of value, whichever is less | Under $5 | HRS § 481B-13 |
| Idaho | 5 years (federal rule) | Federal limits only | Not required | No state gift card law found |
| Illinois | At least 5 years | No fees after purchase | Not required | 815 ILCS 505/2SS |
| Indiana | 5 years (federal rule) | Federal limits only | Not required | No state gift card law found |
| Iowa | 5 years (federal rule) | No deductions for late use (narrow exception) | Not required | Iowa Code § 556.9 |
| Kansas | At least 5 years | None in the first 12 months | Not required | K.S.A. 50-6,108 |
| Kentucky | 5 years (federal; state minimum is 1) | Banned until the card’s expiration date | Not required | KRS 367.890 |
| Louisiana | At least 5 years, printed in capital letters | Banned; one-time handling fee up to $1 | Not required | La. R.S. 51:1423 |
| Maine | No time limit | None except a disclosed issuance fee | Under $5, in person | 33 M.R.S. § 2067 |
| Maryland | 5 years (federal; state minimum is 4) | None in the first 4 years; later fees must be printed | Not required | Md. Code, Com. Law §§ 14-1319, 14-1320 |
| Massachusetts | At least 7 years | Dormancy and service fees banned | After 90% is used, or $5 or less left on a reloadable card | M.G.L. c. 200A § 5D; c. 266 §§ 75C–75D |
| Michigan | At least 5 years | Inactivity and service fees banned | Not required | MCL 445.903e–445.903g |
| Minnesota | Banned | All service fees banned | Not required | Minn. Stat. § 325G.53 |
| Mississippi | 5 years (federal rule) | Federal limits only | Not required | No state gift card law found |
| Missouri | 5 years (federal rule) | Federal limits only | Not required | No state gift card law found |
| Montana | Banned | Banned | Under $5, on cards worth more than $5 | Mont. Code Ann. § 30-14-108 |
| Nebraska | Allowed if printed; 5 years (federal) | Allowed if disclosed | Not required | Neb. Rev. Stat. § 69-1305.03 |
| Nevada | Allowed if printed; 5 years (federal) | Up to $1 a month, only after 3 years of nonuse | Not required | NRS 598.0921 |
| New Hampshire | Banned on certificates of $250 or less | Dormancy and service fees banned | Not required | RSA 358-A:2, XIII |
| New Jersey | Funds never expire on most cards; small issuers 5 years (federal) | Only purchase, reload and replacement fees; small issuers may charge up to $2 a month after 24 months unused | Under $5 | N.J.S.A. 46:30B-42.1; 56:8-110 |
| New Mexico | At least 5 years | Banned | Not required | NMSA 1978 § 57-12-26 |
| New York | At least 9 years | Banned (one-time issuance fee up to $9 on bank cards) | Under $5 | N.Y. Gen. Bus. Law § 396-i |
| North Carolina | 5 years (federal rule) | None in the first year; must be printed | Not required | N.C. Gen. Stat. § 66-67.5 |
| North Dakota | At least 6 years | No service or maintenance fees | Not required | N.D.C.C. § 51-29-02 |
| Ohio | 5 years (federal; state minimum is 2) | None in the first 2 years | Not required | Ohio Rev. Code § 1349.61 |
| Oklahoma | At least 5 years | Banned, with a narrow $1-a-month exception | Not required | 15 Okla. Stat. § 797 |
| Oregon | Banned (except cards sold below face value) | Banned | Under $5, after a purchase | ORS 646A.274–646A.278 |
| Pennsylvania | 5 years (federal rule) | Federal limits only | Not required | No state gift card law found |
| Rhode Island | Banned | Banned | Under $1 | R.I. Gen. Laws § 6-13-12 |
| South Carolina | 5 years (federal; state minimum is 1, or less if printed on the front) | Allowed if disclosed | Not required | S.C. Code § 39-1-55 |
| South Dakota | 5 years (federal rule) | Federal limits only | Not required | No state gift card law found |
| Tennessee | 5 years (federal; state minimum is 2) | None in the first 2 years | Not required | Tenn. Code § 47-18-127 |
| Texas | Allowed if disclosed; 5 years (federal) | Only after 1 year, if reasonable and disclosed | Under $2.50, after an in-person purchase | Tex. Bus. & Com. Code ch. 604 |
| Utah | Allowed if printed; 5 years (federal) | Allowed only if printed | Not required | Utah Code § 13-11-4 |
| Vermont | At least 5 years | Banned (limited issuance fee on bank cards) | Under $1 | 8 V.S.A. §§ 2701–2704 |
| Virginia | Allowed if printed; 5 years (federal) | Dormancy and service fees banned | Not required | Va. Code § 59.1-531 |
| Washington | Banned (limited exceptions) | Banned | Under $5, after a purchase | RCW 19.240 |
| West Virginia | 5 years (federal rule) | Federal limits only | Not required | No state gift card law found |
| Wisconsin | 5 years (federal rule) | Federal limits only | Not required | State does not regulate gift card sales |
| Wyoming | 5 years (federal rule) | Federal limits only | Not required | No state gift card law found |
| District of Columbia | 5 years (federal rule) | Federal limits only | Not required | No D.C. gift card law found |
States That Pay Out Small Balances in Cash
Fourteen states require a store to hand over a small leftover balance in cash when the cardholder asks, so a few dollars do not get stranded on a card:• California: under $15, raised from under $10 on April 1, 2026. Starting January 1, 2027, stores may keep selling cards printed before that change with the old $10 figure through 2028, as long as each register posts a notice that balances under $15 can be cashed out.
• Colorado: $5 or less.
• Connecticut, Hawaii, Montana, New Jersey, New York, Oregon and Washington: under $5, with conditions that vary by state, such as making a purchase first.
• Maine: under $5, when the card is redeemed in person.
• Massachusetts: once 90% of a card’s value has been used, or when $5 or less is left on a reloadable card.
• Texas: under $2.50, after an in-person purchase.
• Rhode Island and Vermont: under $1.
A store that refuses a cash-out the law requires can be reported to the state attorney general; the directory of state consumer protection offices lists each office. Cash-out rules have also produced class actions: the Sally Beauty gift card settlement resolved claims over California low-balance cash-out requests.
When a Store Goes Bankrupt
No federal gift card rule protects a balance when the retailer behind it fails. The FTC warns that a card from a company that files for bankruptcy or goes out of business may be worth less than expected, and the CFPB says a store card may not be redeemable at all if the retailer goes under.What happens is decided in bankruptcy court. When Saks Global filed for bankruptcy in January 2026, the court’s interim order authorized the company to keep honoring gift cards but did not require it to, and required at least 14 days’ notice before it stopped accepting them. A cardholder whose card is no longer honored may be left to file a claim as a creditor in the bankruptcy case. Michigan is one state that requires retailers to keep accepting gift cards during closeout and going-out-of-business sales.
The practical rule is to use a card from a struggling retailer promptly rather than hold it.
Free settlement alerts
Get notified when new class actions open to claims
Join thousands of readers who get the latest class action settlements you may qualify for — delivered straight to your inbox.
Gift Card Scams
Gift cards are a favorite payment method for scammers because the money is hard to trace once the card numbers are shared. In its Consumer Sentinel data for 2024, the FTC recorded 41,120 fraud reports in which people paid with gift or reload cards, with $212 million lost. The FTC’s guidance is blunt: only scammers tell people to buy a gift card and read them the numbers off the back.Anyone who paid a scammer with a gift card should contact the company that issued the card right away, keep the card and the receipt, and report the scam at ReportFraud.ftc.gov. OCA’s guide to avoiding gift card scams covers the warning signs, and a class action over scam-purchased gift cards led to the Apple App Store and iTunes gift card settlement.
Getting the Most Out of a Gift Card
• Read the back of the card and the packaging for expiration terms and fees before buying or giving it.• Keep the receipt; it can prove the purchase date and the amount loaded if the card is lost, stolen or disputed.
• Register the card with the issuer if that option exists, so a lost card can be replaced.
• Ask for cash back on a small leftover balance in the states that require it.
• Spend cards from retailers in financial trouble first.
• Report a store that refuses a balance the law protects to the state attorney general, and an issuer of a bank-network gift card to the CFPB.
Frequently Asked Questions
Can gift cards expire?
Under federal law, the money on a covered gift card cannot expire for at least five years from the date it was bought or last loaded. Several states go further and ban expiration dates on most gift cards, including California, Connecticut, Florida, Minnesota, Montana, Oregon, Rhode Island and Washington. The plastic card itself can expire sooner, but the issuer must provide a replacement.
Are gift card inactivity fees legal?
Federal law allows a dormancy or inactivity fee only after 12 months with no activity, no more than once a month, and only if it is clearly disclosed. Many states ban these fees entirely, including Arizona, Colorado, Florida, Minnesota, New York, Oregon and Washington.
Can I get cash back for a small gift card balance?
In 14 states. California requires cash back for balances under $15 since April 1, 2026; Colorado for $5 or less; Connecticut, Hawaii, Montana, New Jersey, New York, Oregon and Washington for balances under $5 with conditions; Maine for under $5 in person; Massachusetts once 90% of the value is used or $5 or less is left on a reloadable card; Texas for under $2.50; and Rhode Island and Vermont for under $1.
What happens to my gift card if the store goes bankrupt?
There is no federal protection. The bankruptcy court decides whether the company keeps honoring gift cards; it may allow the retailer to keep accepting them but does not necessarily require it. A cardholder whose card is no longer honored may have to file a claim as a creditor. Using a card from a struggling retailer promptly is the safest course.
Do gift card laws cover promotional and loyalty cards?
Generally no. The federal rules exclude loyalty, award and promotional cards, and most state laws carve out promotional cards and cards sold below face value as well, often on the condition that the terms are printed on the card.
Which states have no gift card law of their own?
Alabama, Alaska, Delaware, Idaho, Indiana, Mississippi, Missouri, Pennsylvania, South Dakota, West Virginia, Wisconsin, Wyoming and the District of Columbia rely on the federal rules, which still guarantee at least five years before the money can expire and limit inactivity fees.
Is someone asking me to pay with gift cards running a scam?
Almost certainly. The FTC says only scammers tell people to buy gift cards and share the numbers on the back. Contact the card issuer right away, keep the card and receipt, and report it to the FTC at ReportFraud.ftc.gov.
Where do I complain about a gift card problem?
Complaints about a store’s gift card are handled by the state attorney general’s consumer protection office. Problems with a bank-network prepaid gift card can also be sent to the Consumer Financial Protection Bureau.
Sources
• 15 U.S.C. § 1693l-1 — General-use prepaid cards, gift certificates and store gift cards• CFPB — Regulation E, 12 C.F.R. § 1005.20
• 15 U.S.C. § 1693q — Relation to state laws
• CFPB — Giving or receiving gift cards? Know the terms
• FTC — Gift card tips
• FTC — Avoiding and reporting gift card scams
• FTC — Consumer Sentinel Network Data Book 2024 (PDF)
• In re Saks Global Enterprises LLC, No. 26-90103 (Bankr. S.D. Tex.) — interim order on customer programs (PDF)
• State statutes are linked in the table above; each row was checked against the statute text or official state guidance.